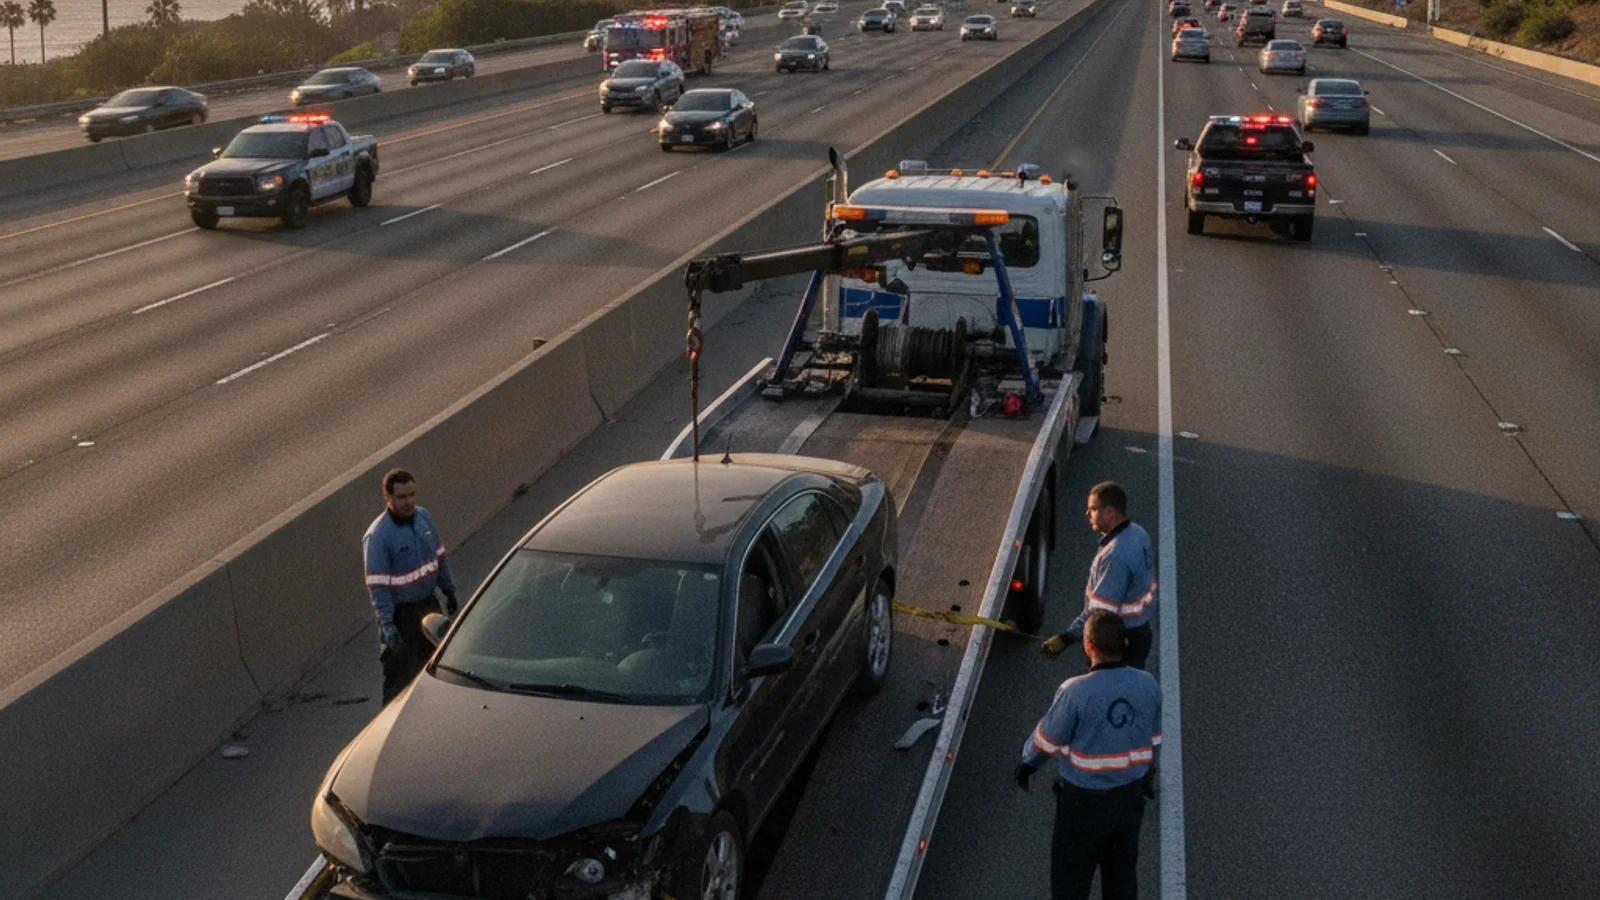
Short answer: it depends on your policy, not on Tennessee law. The state doesn’t require insurers to cover towing. It doesn’t require you to carry that coverage either. Whether your bill gets reimbursed comes down to what you picked when you bought your policy.
What Tennessee actually requires
Tennessee’s Financial Responsibility Law sets the minimum insurance every driver has to carry. That minimum is liability coverage. It pays for injuries and property damage you cause someone else in an accident. It says nothing about towing, roadside help, or getting your own car home. Look for a towing clause in your state-mandated coverage. There isn’t one.
What decides whether your tow is covered
Roadside assistance and towing coverage sits entirely outside that state minimum. It’s an optional add-on. Each insurer decides for itself whether to offer it and what it costs. Nothing in Tennessee law forces a company to include it.
Two Memphis drivers can carry the exact same state-required liability policy. They can still get two different answers when they call about a tow bill. The difference isn’t Tennessee law. It’s whichever optional coverage each of them chose, or skipped, when they signed up. Without that add-on, a liability-only policy was never going to pay for a tow. That’s not a loophole. It’s just what “minimum required” means in Tennessee.
This also means we can’t tell you what your policy covers. We’re a referral line that matches you with a local operator, not an insurance company. We don’t bill insurers directly, and we don’t promise a claim gets paid. Your insurer is the only one who can answer that question for certain.
A membership card isn’t the same thing as insurance coverage
It’s easy to lump every kind of roadside help into one category. A membership club and an insurance towing add-on are two different products. A membership is something you join and pay for directly. It typically covers whichever vehicle you’re driving at the time. An insurance towing endorsement is different. It’s a line item inside your specific auto policy, priced and administered by your insurer.
Carrying one doesn’t tell you anything about whether you carry the other. Check your insurance declarations page first. Separately, think about whether you’ve ever joined a membership club. They live in different places, and only one of them answers the question this article is about.
How to check your own policy before you need it
The best time to find this out is before you’re stuck on the shoulder. A few minutes now saves a confusing call later.
- Pull up your declarations page. It’s the summary page your insurer sends with your policy. It lists every coverage you’re paying for by name.
- Look for “roadside assistance” or “towing and labor.” Those are the two most common names insurers use for this add-on. See one listed, you likely have some towing coverage. See neither, you probably don’t.
- Call the number on your insurance card if the page doesn’t settle it. A quick call to your agent or your insurer’s customer line beats guessing.
- Ask what it actually pays for, not just whether it exists. Some policies cover a breakdown tow to the nearest shop. Others are built around towing after an accident claim. Confirm which one you have.
Knowing the answer before your car breaks down means you’re not reading fine print on the shoulder.
What to do at the roadside when you’re not sure
If you’re already broken down and don’t know what your policy covers, don’t wait on hold to find out. Your safety comes first. A tow that needs to happen now shouldn’t wait on a phone tree.
That’s especially true on the Hernando de Soto Bridge, which carries I-40 across the Mississippi into Memphis. It’s a roughly 1.8-mile span with no shoulder refuge in the arch section, so a breakdown mid-crossing is a real hazard, not just an inconvenience. Coverage questions can wait until you’re off the bridge.
Call (901) 557-8700. The recorded line takes calls 24/7 and matches you with a local operator. Ask for that operator’s full total with mileage included, in writing, before you agree. You pay the operator directly. If your policy includes roadside or towing coverage, submit that receipt to your insurer afterward, and sort out reimbursement on your own timeline instead of holding up the tow to figure it out first.
That order matters. Getting your car out of a dangerous spot is time-sensitive. Figuring out what your insurance will reimburse isn’t. It’s a much easier conversation once you’re already safe.
The bottom line
Tennessee doesn’t mandate towing coverage, and it doesn’t leave you a state law to fall back on if your policy doesn’t include it. The real answer lives on your own declarations page, not in the Tennessee code. Check it before you need it. If you’re already stuck, call (901) 557-8700. Get the matched operator’s total in writing before you agree, and sort reimbursement once your car is somewhere safe.